 Brandinfo
Doctor warns: do not entrust your eyes to an optical shop
1.
 |
The Government’s strategy, approved under Decision No. 928/QD-TTg on May 25, 2026, aims to develop a modern, safe and inclusive financial ecosystem that gives individuals and businesses equal access to financial products and services.
By 2030, the strategy aims for 95 per cent of the population aged 15 and above to have transaction accounts at banks or other authorised institutions, while at least 30 per cent of adults are expected to hold savings deposits at credit institutions or foreign bank branches.
The strategy also emphasises that expanding financial inclusion must go hand in hand with financial system safety, efficiency, sustainability and consumer protection. Financial literacy and public confidence in service providers are important factors influencing whether people, particularly those on low incomes or living in rural and remote areas, use formal financial services.
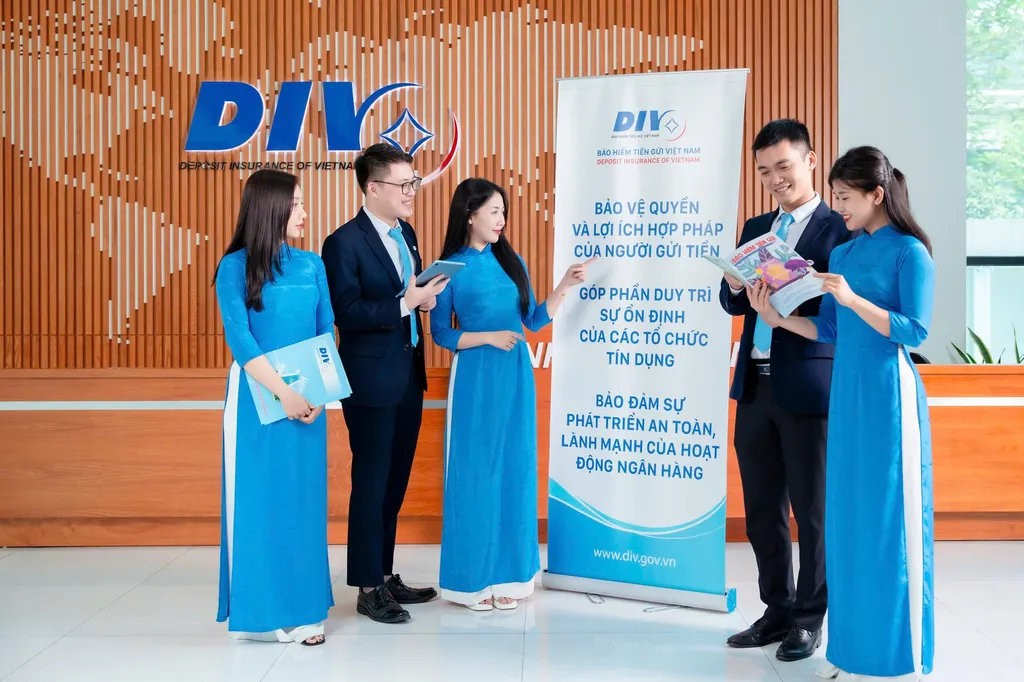
Deposit insurance contributes to these objectives by protecting depositors’ lawful rights and interests and supporting the stability of credit institutions. Although it does not directly provide or expand access to financial services, it helps create a safer and more reliable environment for people to participate in the formal financial system.
Under the Law on Deposit Insurance 2025, which took effect on May 1, 2026, the role of deposit insurance has been strengthened through provisions covering deposit insurance payouts and participation in the handling of credit institutions subject to early intervention or special control.
From July 13, 2026, the deposit insurance coverage limit was raised to VNĐ350 million (US$13,545) under Circular No.05/2026/TT-NHNN. The new law also shortened the maximum payout period from 60 days to 45 days from the date on which the payment obligation arises.
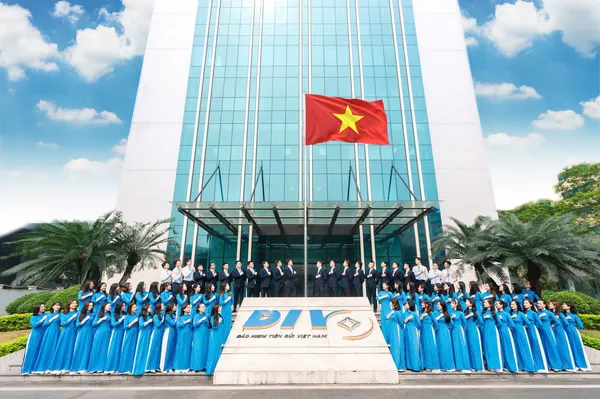
During the first nine months of 2026, DIV reissued deposit insurance participation certificates in the new format to 1,273 institutions and distributed 13,814 deposit insurance participation symbols to make their participation more visible to the public.
Supervision and examination remained important parts of its operations. DIV maintained supervision of all insured institutions during the period and completed inspections of 300 of the 419 institutions included in its examination plan.
The organisation also signed coordination regulations with all 15 regional branches of the State Bank of Vietnam (SBV), establishing a stronger basis for cooperation and information exchange.
In addressing weak credit institutions, DIV assigned staff to participate in special control boards at 31 of the 32 people’s credit funds under special control. It also provided opinions on plans to handle and rehabilitate credit institutions in accordance with regulations.
DIV’s financial resources are another key component of its capacity to protect depositors. Cumulative deposit insurance premium collections reached more than VNĐ11.3 trillion in the first nine months of 2026, while its operational reserve fund was expected to reach approximately VNĐ149 trillion.
The accumulation and prudent management of financial resources provide a basis for meeting insurance payment obligations and carrying out other statutory responsibilities.
Alongside these activities, DIV has continued to diversify its public communication channels and organise events in localities to raise public awareness of deposit insurance policies.
Looking ahead to 2026–2030, the organisation is expected to improve the quality of supervision and examination, expand the use of technology and data to identify risks and provide early warnings, strengthen its financial capacity and enhance its ability to participate in the handling of weak credit institutions.
Financial education will also be important as digital banking, e-wallets, electronic money and new financial products create more opportunities to access financial services while raising questions about consumer protection.
People need to understand the characteristics of different products and distinguish insured deposits from other financial products, including those with functions similar to deposits, so they can understand the protection and entitlements applicable to each.
Under Decision No.1387/QD-NHNN dated June 25, 2026, which sets out the banking sector’s action plan to implement the National Financial Inclusion Strategy for 2026–2030, DIV is among the organisations tasked with coordinating financial education and financial consumer protection activities.
Through cooperation with insured institutions, including people’s credit funds and microfinance institutions, DIV is expected to continue bringing information about deposit insurance policies, deposit safety and depositor rights closer to the public, particularly groups with limited access to financial information.
Brandinfo
 Brandinfo
 Brandinfo
 Brandinfo
 Brandinfo
 Brandinfo
 Brandinfo
 Brandinfo
 Brandinfo
 Brandinfo
 Brandinfo
 Brandinfo
 Brandinfo
 Brandinfo
 Brandinfo