 Brandinfo
Doctor warns: do not entrust your eyes to an optical shop
1.
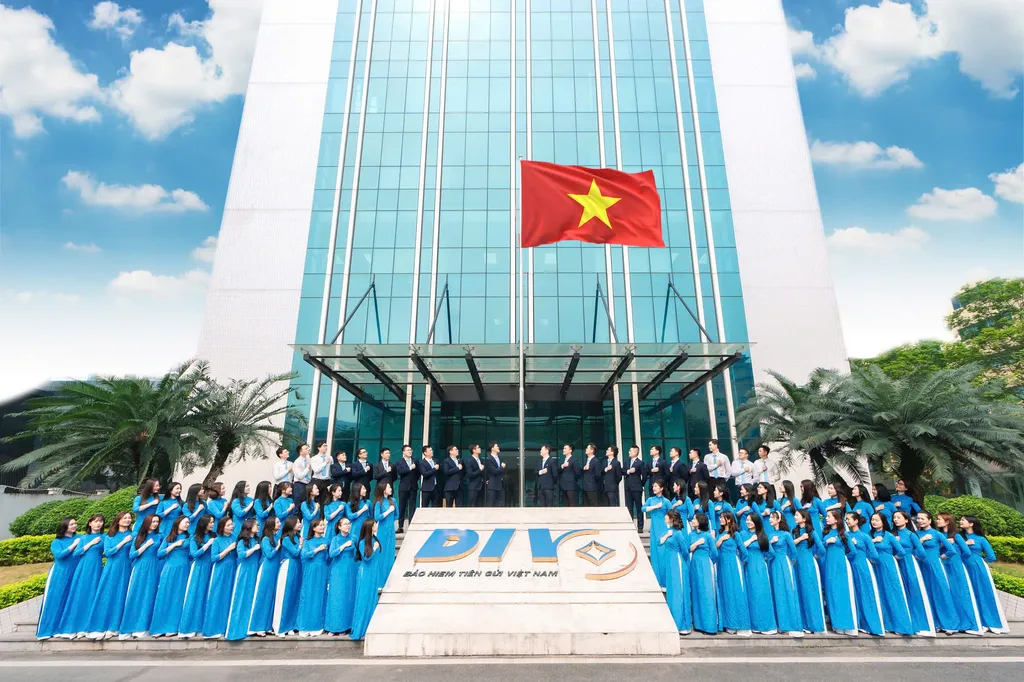 |
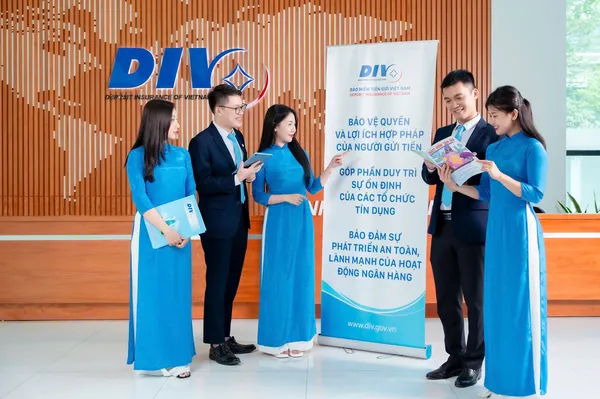
The new law maintains the protection of depositors’ lawful rights and interests as the central objective of deposit insurance, while providing a more comprehensive legal framework for DIV’s responsibilities and powers.
As the banking system undergoes restructuring and increasingly adopts digital technologies and data-driven operations, deposit insurance is expected to play a broader role beyond reimbursement when an insured event occurs.
Under the new framework, DIV can request insured institutions to provide information on insured deposits and other relevant data for inspection purposes. It is also tasked with collecting, analysing and processing information to identify issues that could threaten banking safety and recommend timely action by the State Bank of Vietnam (SBV).
The law also provides for DIV’s participation in early intervention, special control and the resolution of credit institutions. Its responsibilities include taking part in the development of bankruptcy plans for credit institutions under special control, as well as participating in asset management and liquidation in accordance with the law.
The legislation also specifies when deposit insurance payment obligations arise and authorises the SBV Governor to determine coverage limits for different periods.
In certain special circumstances stipulated by law, the SBV Governor may decide to raise the payout limit above the normal level, up to the full amount of a depositor’s insured deposits at the insured institution when the payment obligation arises.
The law also establishes mechanisms for information exchange and access between the central bank and DIV, providing a basis for the organisation to obtain the information needed to perform its statutory duties.
Strengthening financial resources and risk management
These expanded responsibilities require DIV to strengthen its operational capacity, financial resources and risk management framework.
Financial capacity is particularly important to ensuring that the organisation can meet its obligations to depositors. Under the 2025 law, the funding sources of the deposit insurance organisation include State-provided and supplemented charter capital, an operational reserve fund, a development investment fund, a financial reserve fund and other lawful sources of capital.
The operational reserve fund is used for payouts and carry out other duties as prescribed by law.
DIV is also continuing to improve the management and investment of temporarily idle funds within the scope and forms permitted by law. This includes developing criteria for investment portfolios, investment structures, allocation ratios and investment periods, while strengthening controls over investment-related risks.
As a State financial institution operating on a non-profit basis, DIV must manage and use its resources in a way that preserves capital, maintains its ability to fulfil statutory obligations and directly supports the implementation of deposit insurance policy.
Risk management is another priority as the organisation’s remit expands. Financial, legal, operational and data-related risks, as well as those associated with information exchange and coordination, require particular attention.
Technology and data management are also central to improving the effectiveness of depositor protection. DIV is continuing to upgrade its information technology infrastructure, develop its databases and strengthen information connectivity and sharing with SBV units and participating deposit insurance institutions.
Technology applications can support supervision, data collection, analysis and processing, risk detection and the execution of insurance payments. Accurate information on depositors, deposit balances and participating institutions is particularly important for determining compensation entitlements.
Under the 2025 law, DIV is responsible for payouts to eligible depositors within 45 days of the date on which the payment obligation arises. This deadline makes data quality and information-processing capacity directly relevant to the timely delivery of depositor benefits.
Public communication is another part of the framework. Insured institutions are required to coordinate with DIV in communicating deposit insurance policies and legislation, while DIV is responsible for public information activities and training to improve understanding of deposit insurance and related matters.
The document calls for communication to be clear, accessible and tailored to different audiences, with greater use of digital platforms and particular attention to people in rural, remote and underserved areas who may have limited access to financial information.
The Law on Deposit Insurance 2025 provides the legal basis for DIV to expand its work in depositor protection, financial preparedness, risk management, data processing and public communication as part of its responsibilities within Việt Nam’s credit institution system.
Brandinfo
 Brandinfo
 Brandinfo
 Brandinfo
 Brandinfo
 Brandinfo
 Brandinfo
 Brandinfo
 Brandinfo
 Brandinfo
 Brandinfo
 Brandinfo
 Brandinfo
 Brandinfo
 Brandinfo