 Economy
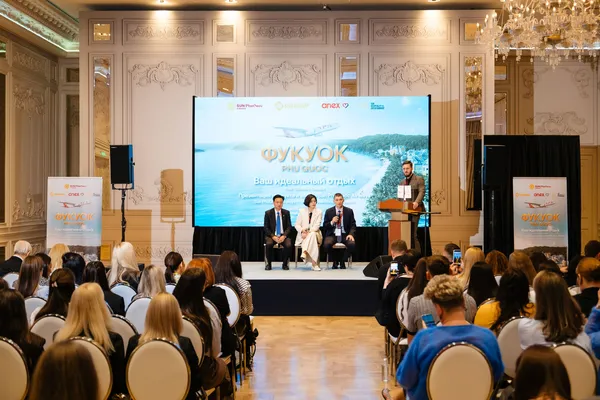
Sun PhuQuoc Airways expands Russian partner network ahead of Moscow route launch
1.
|
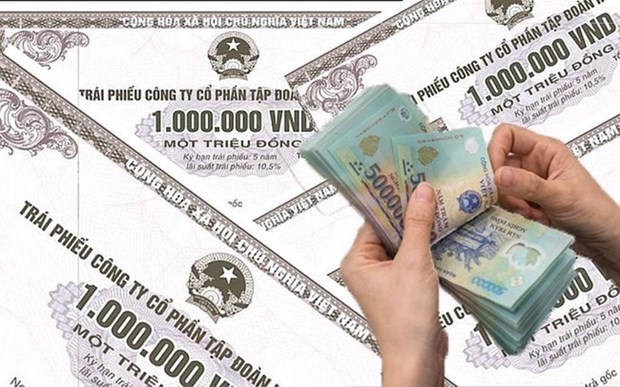
| The corporate bond market recorded a total issuance value of VNĐ179.4 trillion (US$6.79 billion) in the third quarter, a 26 per cent decline from the previous quarter. VNA/VNS Photo |
HÀ NỘI — Corporate bond interest rates have hit 13 per cent per annum, gradually approaching the peak of 14 per cent seen during the 2022-2023 period.
According to the third-quarter bond market report by S&I Ratings, bond issuance rates have continued to rise across various sectors. Specifically, the average coupon rate has increased by approximately 2.5 percentage points from its low in 2025. However, the pace of this rise slowed significantly in the third quarter as rates neared the 2022-2023 peak levels.
Bond issuance rates for real estate firms and other corporate entities reached as high as 12.5-13 per cent per annum.
For the banking sector, the average bond issuance rates also reached 8.85 per cent per annum, surpassing the 8.7 per cent average recorded in 2022. Some bond issues even carried rates exceeding 10 per cent per annum.
According to the report, bond issuance activity slowed in the third quarter of 2026 following a sharp surge in the second quarter. Specifically, the corporate bond market recorded a total issuance value of VNĐ179.4 trillion (US$6.79 billion) in the third quarter, a 26 per cent decline from the previous quarter.
Much like the pattern observed in 2025, following a quiet first quarter, bond issuance activity spiked in the second quarter before undergoing a market-cycle-driven correction in the third quarter. Nevertheless, the issuance value for the third quarter remains 8 per cent higher than in the same period last year.
In contrast to the broader trend, public bond offerings reached an all-time high. During the third quarter, 16 public bond offerings were successfully completed, totaling VNĐ31.6 trillion, a 55 per cent increase year-on-year.
Commercial banks continued to account for the largest share of this fundraising channel, with 8 separate offerings, typically ranging in value from VNĐ1 trillion to VNĐ3 trillion each. Notably, Agribank alone successfully issued VNĐ15 trillion in such bonds.
Additionally, securities firms, as well as finance and consumer finance companies, also participated in public bond offerings, though most of these issuances were valued at less than VNĐ1 trillion.
Pressure to raise capital is further driven by the need to repay maturing bonds. S&I Ratings estimates that approximately VND 93 trillion in corporate bonds will mature in the fourth quarter of 2026, the highest volume for the year. Of this, real estate bonds account for about VNĐ46.9 trillion, representing nearly half of the total maturing value.
Looking ahead to 2027, the total value of maturing bonds is projected to reach VNĐ276 trillion, an increase of 22 per cent compared to 2026. The real estate sector alone accounts for approximately VNĐ156 trillion in maturing bonds, equivalent to 57 per cent of the total market value.
The report indicates that new bond issuance in the coming period will serve both to fund projects and to restructure existing debt obligations. However, both domestic and international interest rates are projected to remain high, at least through the first half of 2027. This increases the cost of capital, particularly for businesses with high financial leverage or significant capital-raising requirements.
Against this backdrop, Vietnamese enterprises and financial institutions are gradually diversifying their funding sources, including by accessing international capital markets. Nevertheless, any potential interest rate advantages must be weighed against the costs associated with deal arrangement, credit ratings, and foreign exchange risk hedging.
S&I Ratings anticipates that the need for capital raising and refinancing will continue to support the corporate bond market in the medium term. That said, high interest rates remain a challenge for both the cost of capital and issuance capacity, suggesting that the market will require more time to restructure toward a more sustainable footing. — BIZHUB/VNS
Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy