 Business Beat
Another 148 sets of martyrs’ remains recovered at Lê Thị Riêng Park
1.
 |
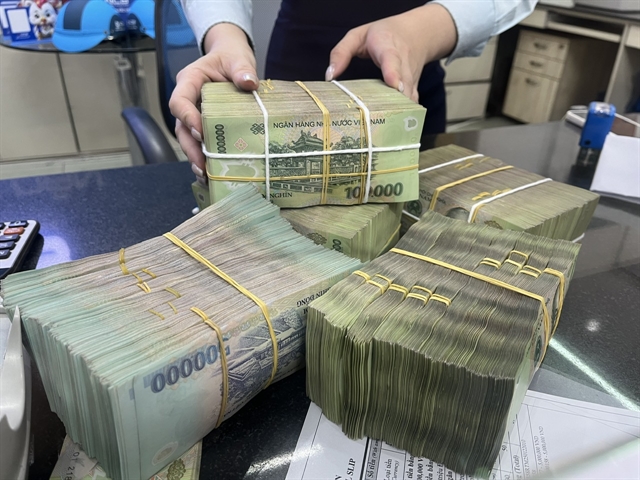
| The net interest margin of the entire banking sector is forecast to decline by two basis points to 3.1 per cent in 2027. — VNA/VNS Photo |
Compiled by Thu Hà
As net interest margins (NIM) continue to see downward pressure, banks are shifting their strategies toward non-credit revenue sources to boost profitability without depleting their equity capital.
A banking sector report released recently by the MBS Securities Company showed that in the third quarter of 2026, NIM of the entire banking system was facing further downward pressure due to high deposit interest rates, particularly at banks with rapid credit growth or those heavily reliant on term deposits.
SSI Research analysts projected that banks' NIM will decline by two basis points to 3.1 per cent in 2027.
Banking expert Lê Hoài Ân noted that NIM is expected to remain under pressure from multiple fronts through the fourth quarter of 2026, as well as into 2027.
According to Ân, the primary factor is that credit growth has consistently outpaced deposit growth. As of September 28, system-wide credit growth reached 10.9 per cent, while deposit growth stood at 9.8 per cent. Although the gap between credit and deposit growth has narrowed significantly, system liquidity remains strained, compelling banks to compete for deposits – a dynamic that drives up the cost of funds.
Meanwhile, the ability to adjust lending rates is constrained by market competition and the Government’s imperative to support economic growth.
According to Ân, the cost of funds is rising faster than the pace that lending rates can be adjusted, which has eroded profit margins across the entire sector.
He said the practice of using short-term capital to fund medium- and long-term loans creates risks related to maturity mismatches and interest rate repricing. Consequently, when the cost of funding adjusts more rapidly than the yield on assets, the NIM inevitably shrinks.
Another significant factor is the shifting structure of credit. In recent years, the momentum for credit growth has shifted from retail lending toward corporate loans and large-scale investment projects.
“A key characteristic of this client segment is the large size of individual loans, yet profit margins are typically lower than those in retail lending – a result of the clients' strong bargaining power and intense competition among banks. As the share of these loans increases, NIM across the entire banking system may continue to face structural pressure,” Ân said.
Đỗ Minh Trang, director of the Market Analysis and Strategy Department at the ACB Securities Company (ACBS), noted that while the average cost of funds for banks has risen by approximately one percentage point, the yield on interest-earning assets has increased by only about 0.7 percentage points, leading to an erosion of the NIM.
With 70 per cent of bank deposits concentrated in short-term tenors of 3-6 months, interest expenses paid to depositors rise rapidly whenever interest rates climb, according to Trang.
Conversely, a significant 40-50 per cent portion of the loan portfolio consists of medium- and long-term loans, which have a slower frequency for interest rate adjustments, preventing interest income from keeping pace with the rising costs.
Sustainable growth
Ân noted that in an international context, NIM in Việt Nam remains significantly higher than in banking systems in China, the Republic of Korea or Japan. For instance, the NIM for Chinese banks is only around 1.4 per cent, far lower than the levels seen in Việt Nam.
While differences in market structure and monetary policy exist, this suggests that a low NIM is not an anomalous phenomenon in the development of a banking system.
However, if banks continue to rely primarily on deposit-taking and lending to profit from interest rate spreads, a narrowing NIM will inevitably put pressure on profitability. In other words, even as asset bases and credit volumes expand, a shrinking NIM means that each additional unit of credit generates less profit than before.
Continuous credit expansion amid low profit margins also increases risk-weighted assets, which erodes the capital adequacy ratio and forces shareholders to inject additional capital.
Given this reality, banks must diversify their sources of profit. According to Ân, non-interest income will play an increasingly vital role in the overall profitability of banks.
 |
| In the long term, banks need to develop sustainable non-interest income sources, such as those from payments, wealth management, insurance and corporate financial services. — VNA/VNS Photo |
"In the long term, banks need to develop sustainable non-interest income sources, such as those from payments, wealth management, insurance and corporate financial services," Ân said.
He added that the profit outlook for late 2026 and early 2027 will not be determined solely by the pace of credit growth. Rather, it will increasingly depend on a bank's ability to manage the cost of funds and provisioning expenses, as well as its success in diversifying revenue sources.
Trang agreed, noting that relying solely on the spread between deposit and lending rates will inevitably lead to a decline in bank profitability over time. Attempting to maintain the NIM by pushing up lending rates merely shifts risk onto borrowers, which can easily result in an increase in bad debts, Trang said.
Banks are currently shifting their strategies toward non-credit revenue sources to boost profits without depleting their equity capital. This strategic pivot focuses on developing recurring service offerings, such as payments, insurance and wealth management, that span the entire customer lifecycle.
According to Trang, instead of engaging in a costly race to attract savings deposits, banks are encouraging customers to shift their capital into assets under their management, such as equity fund certificates or bonds within their ecosystem.
Although the fee income generated from fund management may be smaller than the traditional NIM spread, the continuous circulation of capital and the cultivation of deep and long-term relationships to facilitate the cross-selling of various financial products can generate a total revenue stream that effectively compensates for any compression in NIM, all without creating new non-performing loans or additional provisioning burdens, Trang said. — BIZHUB/VNS
Business Beat
 Business Beat
 Business Beat
 Business Beat
 Business Beat
 Business Beat
.jpg) Business Beat
 Business Beat
 Business Beat
 Business Beat
 Business Beat
 Business Beat
 Business Beat
 Business Beat
 Business Beat