 Economy
Video creation contest launched to promote culinary tourism
1.
|
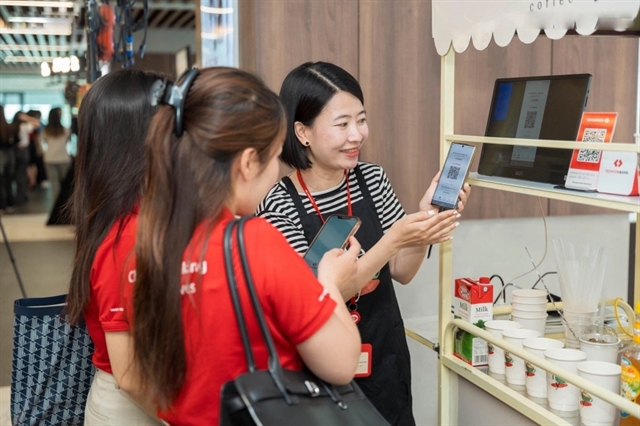
| A household business owner explores T-Shop’s features at an event. — Photo One Mount |
HÀ NỘI — Banks are no longer present only when people deposit their savings, businesses take out loans or a money transfer is made. They are present at more and more touchpoints across the digital economy.
Moving beyond their traditional role as financial intermediaries, banks are becoming architects of digital ecosystems, connecting money flows, data and services, and helping drive the digital economy and digital society.
Five years after the State Bank of Vietnam (SBV) issued Decision 810/QĐ-NHNN on the banking sector’s digital transformation plan, many of its ambitions have become reality.
Opening accounts with electronic identification, biometric authentication, one-touch payments and online lending, once seen as technologies of the future, are now part of everyday life.
Digital transformation has changed not only how individuals and businesses access banking services, but also the scale and scope of banking activities. The value of cashless payments has exceeded VNĐ362 quadrillion (US$14 trillion), equivalent to 28 times GDP, while nearly 89 per cent of people aged 15 and above now have a payment account.
Cashless payment transactions in the first five months of this year increased 34.8 per cent in volume and 11.5 per cent in value year-on-year. Internet-based transactions rose 52.8 per cent in volume and 24.6 per cent in value, while mobile transactions increased 33.6 per cent in volume and 1.7 per cent in value, according to the SBV.
Deputy Prime Minister Nguyễn Văn Thắng said Việt Nam is witnessing a transformation in consumer behaviour and the management of money flows. Digital payments have evolved from a new option into an essential part of the economy, integrating banking with commerce, healthcare, education, transportation, tourism, public services and other digital platforms.
This expanding ecosystem is also changing what customers expect from banks. For household businesses, their needs are no longer limited to loans or payment accounts, but for integrated tools to manage their operations.
Techcombank, for example, has developed an ecosystem for household businesses that combines online account opening, sales management software, electronic invoices, digital signatures and tax support. Through a single platform, business owners can manage sales, accept QR code payments, issue invoices, track revenue and reconcile cash flows.
The same shift is taking place in corporate banking. BIDV has developed platforms including BIDV Direct, BIDV TradeUp, Supply Chain Finance and Open API, enabling integration with corporate ERP systems, real-time cash flow management, supply chain financing and trade finance. Financial services are becoming embedded in business operations rather than remaining separate transactions.
Nam A Bank has taken this integration further with its Digital Citizen Station, which combines banking transactions with public service payments, information verification and other digital utilities. Such models demonstrate how financial services are becoming increasingly intertwined with essential services in people’s daily lives.
From financial intermediaries to digital ecosystem builders
The transformation is changing the basis of competition in banking. Competitive advantages once centred on capital, branch networks and transaction volumes. Now, the ability to connect data, integrate services and meet customers’ needs through a single platform is becoming a key differentiator.
According to Thời Báo Ngân Hàng (Banking Times), Phạm Anh Tuấn, director general of the SBV’s Payment Department, said the banking sector is one of the pioneers of digital transformation. Its objective is to build an increasingly comprehensive financial ecosystem that places individuals and businesses at the centre while contributing to the development of the digital economy and digital society.
The implementation of Politburo Resolution 57-NQ/TW on breakthroughs in the development of science and technology, innovation and national digital transformation has provided an important foundation for the banking sector to enter a new phase of development. As the lifeblood of the economy, the banking sector is committed to maintaining its pioneering role in this digital transformation.
In the next phase, focus will be placed on strengthening the regulatory framework, upgrading technology infrastructure, enhancing cybersecurity and developing shared databases. Greater data sharing between the banking sector and other industries will also help expand digital ecosystems and enable faster, safer and more efficient services.
The sector will also strengthen international cooperation, invest in digital transformation, expand technology-driven products and services, and promote financial education so that individuals and businesses can use digital banking safely and effectively.
These priorities are reflected in Decision 3579/QĐ-NHNN approving the Banking Sector Digital Transformation Strategy through 2030. Under the strategy, individuals and businesses remain the centre, primary actors and driving force of digital transformation, while the SBV provides strategic direction and creates a favourable environment for innovation and technology adoption.
The goal is no longer simply to make banking services more convenient, secure and intelligent. It is to create seamless experiences across channels and platforms and integrate banking more deeply into economic and social activities.
Data is at the heart of this transformation, serving as both a critical asset and a strategic resource. By unlocking its value, banks can create more touchpoints across everyday life, strengthen their competitiveness and play an increasingly important role as part of the digital economy's infrastructure. — VNS
Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy