 Politics & Law
NA Standing Committee scrutinises proposed tax exemptions for education sector
1.
|
|
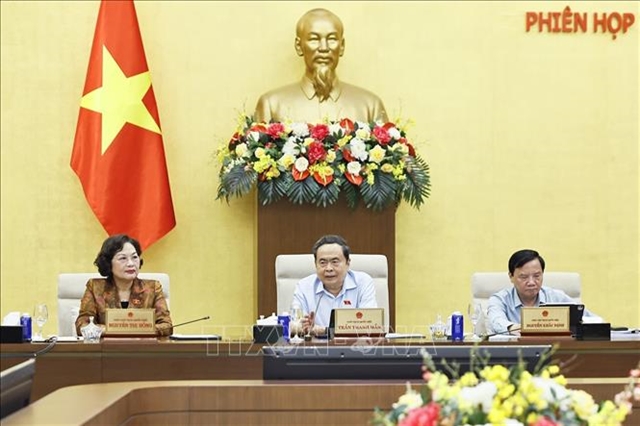
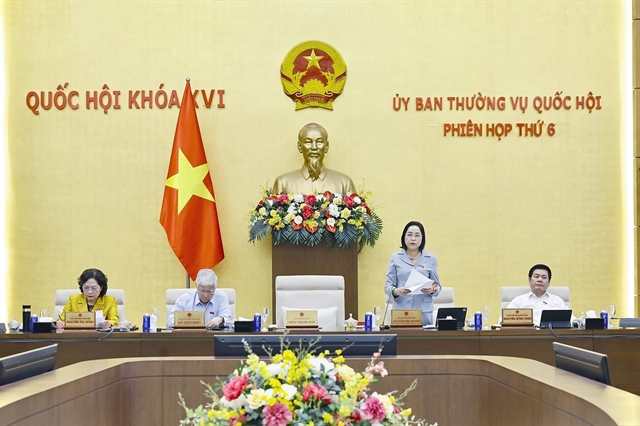
| NA President Trần Thanh Mẫn chaired the NA Standing Committee's meeting on Tuesday. — VNA/VNS Photo |
HÀ NỘI — The National Assembly (NA) Standing Committee on Tuesday discussed a draft law amending and supplementing a number of articles of the Law on Corporate Income Tax, the Law on Non-Agricultural Land Use Tax and the Law on Personal Income Tax.
According to the Government’s proposal, the draft aims to institutionalise Party policies on tax incentives for domestic educational establishments, contributing to creating breakthrough on education and training development under Resolution No. 71-NQ/TW and financial and land tax policies under Resolution No. 21-NQ/TW.
The draft proposes amendments concerning corporate income tax exemptions and reductions and conditions for tax incentives; tax rates, registration, declaration, calculation and payment, and exemptions under the Law on Non-Agricultural Land Use Tax; and other cases eligible for personal income tax exemptions or reductions.
Presenting the verification report, Chairman of the NA Committee for Economic and Financial Affairs Phan Văn Mãi said the committee supports exempting public educational establishments from corporate income tax and non-agricultural land use tax on land used for education and training.
However, it said there are insufficient political, legal and practical grounds for completely exempting corporate and personal income tax on income from providing meals to educational and medical establishments.
Such tax exemptions will not directly ensure compliance with food safety regulations, while there is insufficient basis to confirm that the benefits would be used to reduce meal prices or improve meal quality, it noted.
Regarding the proposed corporate income tax exemption for non-profit private educational establishments, the committee called for further study and clear criteria defining “non-profit” status, eligible areas, non-distribution of profits and reinvestment in education.
It suggested that exemptions apply only to income directly generated from educational activities, while independent business and commercial activities should be separately accounted for and taxed as prescribed.
Commenting on the proposed exemption for enterprises providing meals to educational and medical establishments, National Assembly President Trần Thanh Mẫn called for further study of the policy in conjunction with measures on tuition exemption, public healthcare and school meals.
He stressed that the policies have humanitarian significance but their practical basis, impacts and implementation resources must be fully assessed.
Regarding tax exemptions for public and non-profit private educational establishments, the NA President requested clarification of shortcomings in current regulations and assessment of impacts on State budget revenues.
For non-profit private schools, he called for clear criteria, eligibility conditions and the scope of tax-exempt income to prevent incentives from being extended to unrelated business, financial investment, property leasing or commercial services.
He asked that the scope and level of non-agricultural land use tax exemptions for educational land be clearly defined, particularly where land is used for multiple purposes, to ensure transparent and consistent financial obligations.
Concluding the discussion, Vice President of the National Assembly Nguyễn Thị Hồng said the NA Standing Committee basically agreed on the need to amend the corporate income tax and non-agricultural land use tax laws.
She asked the Government, Ministry of Finance and relevant agencies to continue reviewing the draft, including the proposed personal income tax policy on meal provision, and ensure the scope, beneficiaries, conditions and level of tax incentives are clearly defined.
The Government was also requested to assess impacts on the State budget, prevent policy abuse and ensure consistency with relevant laws and international treaties. — VNA/VNS
Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
.jpg) Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law