 Economy
Restoring polluted rivers requires integrated solutions
1.
|
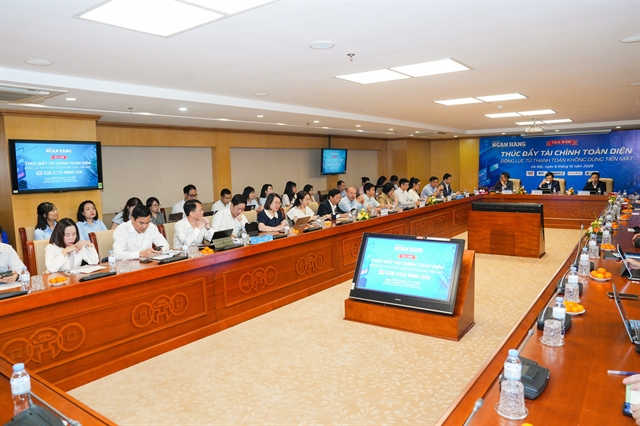
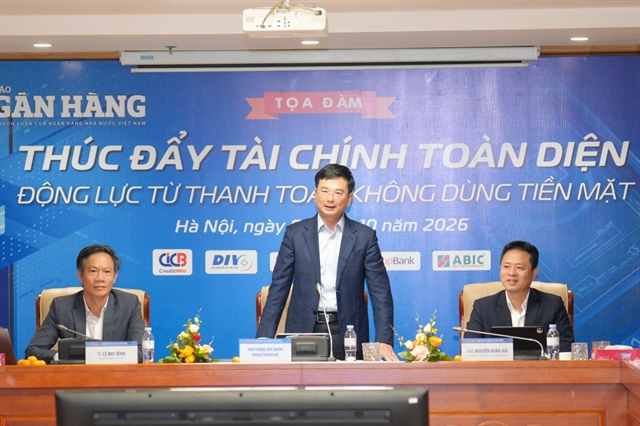
| A view of the seminar. — VNS Photo |
HÀ NỘI — Cashless payments are now key drivers of financial inclusion, aligning with the National Financial Inclusion Strategy for the 2026-2030 period, deputy governor of the State Bank of Vietnam (SBV) Phạm Thanh Hà said Tuesday.
Speaking at the seminar on financial inclusion, Hà said, “Cashless payment is not merely a change in payment methods in Việt Nam, but it is becoming a key driver of the country’s financial inclusion."
According to Hà, as individuals and businesses increasingly utilise accounts and digital payments, financial services become more deeply integrated into daily life and business operations. This process generates transaction data and expands access to appropriate financial products, such as savings, credit, insurance, and other services.
“Therefore, it is essential to continue linking the development of non-cash payments with national financial inclusion goals for the 2026-2030 period, placing the ability of individuals and businesses to access and use financial services effectively, safely and equitably at the core,” he noted.
Under the National Financial Inclusion Strategy, by the end of the 2026-2030 period, 95 per cent of the population aged 15 and older should have a transaction account at a bank or other authorised institution. The value of non-cash payments aims to reach 30 times the GDP, with expansion of access to financial services in rural, remote, isolated, border, and island areas.
To meet these goals, Hà said that payments and digital policies must be streamlined to ensure consistency and transparency, while fostering innovation, ensuring system security, and protecting users' legitimate rights. This should thoroughly develop payment and digital finance infrastructure to enhance domestic interoperability and prepare for cross-border retail payment connectivity.
Hà said financial access must be made for underserved groups and regions in the agricultural and rural sectors, remote, mountainous and island areas. These needed to be promoted to low-income groups, small and medium-sized enterprises, business households, and vulnerable populations with developing products and delivery channels that are simple, convenient, cost-effective, and tailored to actual needs.
Hà also emphasised the need to enhance financial literacy and digital skills, as well as strengthen safety, security, fraud prevention, and the protection of user data and rights. Equipping citizens with knowledge, skills, and confidence is central for bolstering regular, safe, and effective use of financial services.
“This also serves as the foundation for cashless payment to more fully realise its role as a gateway, bringing individuals and businesses closer to formal financial services and thereby contributing to the achievement of national financial inclusion goals in a substantive, safe and sustainable manner,” Hà added.
|
| Deputy governor of the State Bank of Vietnam (SBV) Phạm Thanh Hà speaks at the event. —VNS Photo |
According to Nguyễn Thị Thu, deputy director of the SBV’s Payment Department, payment networks are continuing to expand through new models, reaching rural areas and customer segments with limited access to financial services.
As of June 30, 2026, there were approximately 5,700 payment agent locations and 11.45 million registered mobile money accounts, of which 6.18 million were active. There were 5,158 mobile money business locations operating at the commune level nationwide.
QR codes and mobile payment methods are helping bring financial services closer to the public, especially in areas where establishing physical transaction networks was formerly difficult. The expansion of low-cost payment acceptance points also narrows gaps in service access between urban and rural areas.
Nguyễn Thanh Tùng, Deputy CEO of the National Payment Corporation of Vietnam (NAPAS), said the success of financial inclusion would be both measured by the number of accounts opened and whether those accounts are used conveniently, frequently, and effectively in everyday activities.
Tùng believes that digital payment infrastructure plays a pivotal role in scaling this process. While banking apps, e-wallets, cards, and QR codes are what users directly see, the underlying infrastructure ensures that transactions are connected, processed, and completed quickly, accurately, and securely.
“The infrastructure facilitates connectivity among individuals, banks, businesses, and service providers, enabling users to make payments anytime, anywhere, via various methods. Utilising shared infrastructure also helps reduce costs associated with individual connections and cash processing, while paving the way for service expansion into rural and remote areas as well as to underserved customer segments,” he said.
For payment infrastructure to continue driving financial inclusion, Tùng said that five key elements must be ensured: accessibility; practicality; connectivity; scalability; and safety and reliability. The infrastructure must operate continuously, support transaction inquiries, and strengthen fraud prevention, while simultaneously expanding connectivity between the public and banks, businesses, and service providers.
"Every new connection within the digital payment infrastructure represents another opportunity to bring individuals, business households, and enterprises closer to financial inclusion," Tùng said. — BIZHUB/VNS
Economy
 Economy
 Economy
 Economy
.jpeg) Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy