 Economy
New rice trade rules take effect from October
1.
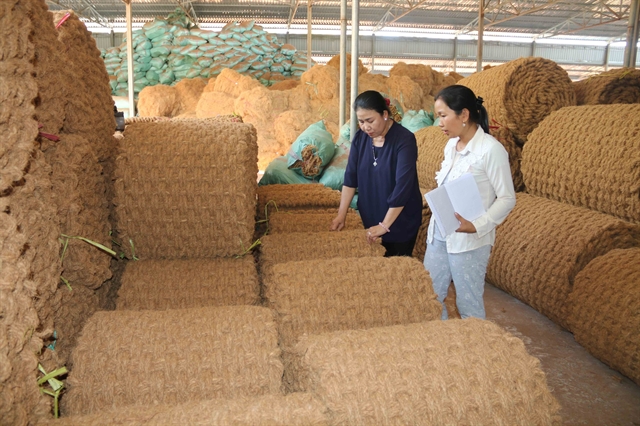 |
| Út Mừng Co., Ltd. specialises in producing goods from coconut coir. The operations of the central SME development fund and local credit guarantee funds remain sluggish. — VNA/VNS Photo Thanh Hòa |
HÀ NỘI — State-backed funds designed to help small and medium-sized enterprises (SMEs) access finance need restructuring to enhance efficiency and unlock finance, officials have said.
According to the Ministry of Finance, the operations of the central SME development fund and local credit guarantee funds remain sluggish, requiring new approaches to improve their effectiveness.
The ministry said that Việt Nam currently has 19 of 24 local credit guarantee funds still operating. Over 13 years of operation, the local credit guarantee funds have provided guarantees worth about VNĐ43 trillion (US$1.7 billion) through 2,100 contracts, benefiting around 1,000 businesses.
They have had to repay about VNĐ130 billion on behalf of borrowers, of which only about VNĐ24 billion has been recovered.
The SME Development Fund has disbursed about VNĐ1.4 trillion over the same period and recovered around VNĐ1.2 trillion.
These figures emphasise a persistent challenge for SMEs, which account for about 98.4 per cent of the number of enterprises in Việt Nam but continue to face difficulties accessing capital.
Finance Minister Ngô Văn Tuấn said new approaches are needed to improve the operations of the central development fund and local credit guarantee funds.
Debt recovery becomes difficult if loans are provided without being able to monitor borrowers' cash flows, Tuấn said. He added that commercial banks have systems to monitor collateral, cash flows, revenues and expenses, while the funds lack comparable management systems and largely operate through entrusted lending arrangements.
Lê Quang Mạnh, NA secretary general and chairman of the NA Office, said the example of the SME Development Fund and credit guarantee funds raised questions about the effectiveness, risks and fairness of using public resources to support individual businesses.
He called for a shift in policy thinking from support to development. Rather than focusing mainly on individual incentives and support schemes, authorities should prioritise improving the business environment, simplifying procedures and reducing costs, Mạnh said.
Restructure rather than abolish
 |
| A customer conducts a transaction at VietBank in Cần Thơ. Việt Nam currently has 19 of 24 local credit guarantee funds still operating. — VNA/VNS Photo Thu Hiền |
Phan Văn Mãi, chairman of the NA’s Committee for Economic and Financial Affairs, said the SME Development Fund should not be scrapped simply because it has performed poorly.
Its limited effectiveness could stem from weaknesses in its organisation and operating mechanisms, he said.
As access to capital is extremely important for SMEs, Mãi proposed restructuring the fund and linking it with credit guarantees and interest rate support schemes.
These funds could focus on credit guarantees, interest rate subsidies, support for access to production and business premises and start-up assistance, he said.
Nguyễn Thanh Hải, chairwoman of the NA’s Committee on Science, Technology and Environment, said there is a lack of sufficient data showing the impact on businesses after support was provided when assessing the efficiency of the funds.
She called for additional indicators covering productivity, revenue, employment, digital transformation, technological innovation, access to finance, business survival rates and participation in value chains.
The effectiveness of support should be measured not just by the amount of resources allocated or the number of businesses receiving assistance, but by tangible results, she said.
For new financing mechanisms such as co-investment, blended finance, seed capital and support vouchers, Deputy NA Chairwoman Nguyễn Thị Hồng said authorities need to clearly define the responsible parties, powers, funding sources, management arrangements, risk-sharing mechanisms, post-audit procedures and accountability.
She also stressed the need to conduct a comprehensive and quantitative assessment before deciding the future of the funds.
A fund's weak performance alone should not be enough to determine whether it is maintained or dissolved, she said. Authorities need to establish how many businesses have benefited, what impact the support has had and why the instruments have failed to deliver better results.
Possible options include maintaining the funds while substantially changing their operating mechanisms, strengthening their financial capacity, reorganising or merging them, or dissolving them.
For the SME Development Fund and credit guarantee funds, Hồng called for a comprehensive assessment of their operations and effectiveness, including the causes of their shortcomings, before comparing options for continued operation with major reforms, merger, reorganisation or dissolution.
If the funds are not maintained, replacement mechanisms must be designed to perform their risk-sharing functions and ensure that businesses' access to finance is not disrupted or reduced, she said. — VNS
Economy
Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy