 Economy
A boost to the grassroots healthcare system
1.
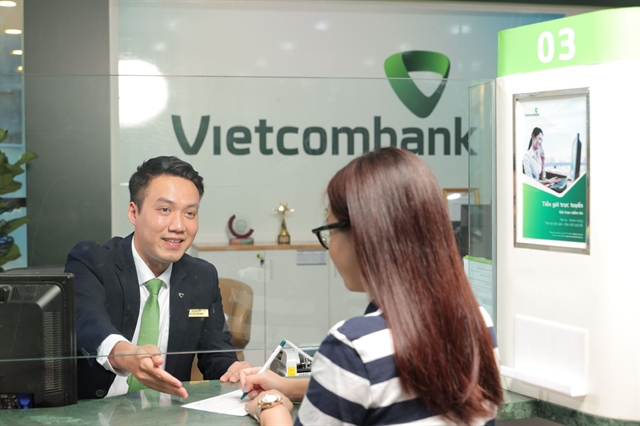 |
| VCB maintained stable overdue loan ratios, supported by diversified lending portfolios and prudent underwriting practice with lower exposure to higher-risk real estate sectors. — VNA/VNS Photo |
HÀ NỘI — The return on average assets (ROAA) of the banking sector will likely remain stable at around 1.5 per cent in the second half of 2026, but profitability divergence among banks will increase, with large banks outperforming peers on stronger margins and diversified earnings, analysts forecast.
In a recent report on the banking sector, analysts from the Vietnam Investors Service Rating said the sector’s ROAA rose by 10 basis points quarter-on-quarter to 1.51 per cent in the first half of this year, driven by net interest margin (NIM) improvements at some State-owned banks and large private banks.
According to the analysts, these banks offset rising deposit costs through higher lending yields, supported by rapid growth in long-term, higher-yielding real estate (such as MBB and HDB) and unsecured retail lending (such as TCB), and faster loan repricing at State-owned banks (such as VCB and CTG). Profits at large private banks (such as TCB and HDB) were further supported by investment banking-related fee income at their securities subsidiaries.
In contrast, smaller banks’ ROAA declined by 20 basis points on average from the prior year, reflecting margin compression from higher deposit competition and deposit costs (such as MSB and SSB), and higher credit costs (such as SGB, VAB, PGB, BAB and STB).
“We expect sector ROAA to be stable at around 1.5 per cent, as rising credit costs across the sector offset NIM improvement at selected large banks,” the analysts said.
In the report, the analysts noted that credit divergence widened across Vietnamese banks in the first half of this year as elevated interest rates and tight operating conditions stemming from prolonged geopolitical tensions further increased funding pressures and asset risks.
Large banks and State-owned banks outperformed their peers, supported by stronger funding profiles and improving profitability, while smaller banks remained constrained by rising credit costs and weaker margins amid intense deposit competition.
“We expect these credit gaps to persist in the second half of 2026, with asset, funding and liquidity risks remaining key credit challenges for banks. In addition, rapid loan growth and ongoing cash dividend payouts will keep sector loss absorption buffers modest,” the analysts forecast.
According to the report, asset risks broadened across banks, as higher borrowing costs and tight operating conditions weakened borrower repayment capacity.
Specifically, sector overdue loan ratios increased to 3.8 per cent in the first half of 2026 from 3.3 per cent in 2025, reflecting broader stress across retail and corporate borrowers.
Retail loan delinquencies also expanded beyond small and mid-sized banks (such as OCB, LPB, SGB, VAB, KLB and ABB) to large banks (such as TCB), particularly in mortgage and/or household business loans, as elevated interest rates and rising household leverage strained borrowers’ debt serviceability.
Corporate credit risks also emerged at several large banks (such as HDB, STB and CTG), particularly among real estate, F&B and agricultural borrowers, as higher financial and logistics costs squeezed margins and cash flows.
In contrast, VCB and ACB maintained stable overdue loan ratios, supported by diversified lending portfolios and prudent underwriting practice with lower exposure to higher-risk real estate sectors.
“We expect sector asset risks to remain high through the second half of 2026 amid elevated interest rates, particularly at banks with significant retail exposure and rapid growth in higher-risk real estate lending,” the report noted.
According to the report, sector loss absorption buffers remained modest amid rising asset risks in the first half of this year, of which sector loan loss coverage ratio fell to 79 per cent, four percentage points lower than end-2025, amid rising loan delinquencies, particularly at some State-owned banks such as CTG and BID.
The analysts forecast that the sector loss absorption buffers will deteriorate in the second half of 2026, pressured by rapid loan growth and cash dividends at State-owned banks. — BIZHUB/VNS
Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy