 Economy
Switching off 2G: An inevitable step in the 5G era
1.
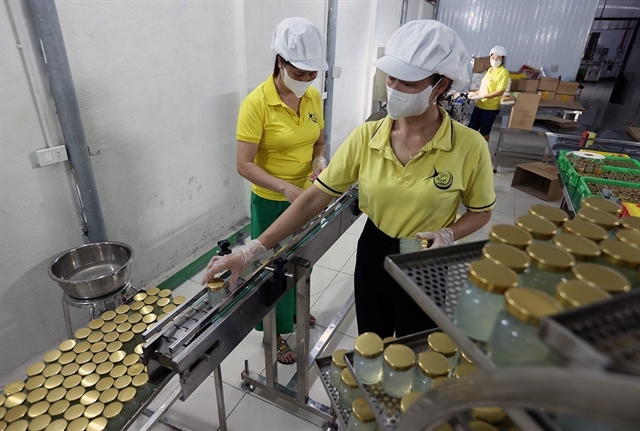 |
| A bird’s nest beverage company in Thanh Hóa Province. The Ministry of Finance is raising public comments for a draft decree detailing the National Assembly’s Resolution 43/2026/QH16 on cutting personal and corporate income tax by 30 per cent in 2026 and 2027. — VNA/VNS Photo Vũ Sinh |
HÀ NỘI — The Ministry of Finance is seeking public comments on a draft decree on cutting personal and corporate income tax by 30 per cent in 2026 and 2027 for business households,
The move is part of the National Assembly’s Resolution 43/2026/QH16 and will apply to individuals and organisations with annual revenue of no more than VDNĐ10 billion (US$379,000).
For personal income tax (PIT), the proposed 30 per cent reduction would apply to households and individuals with annual revenue of below VND10 billion. Taxpayers whose projected revenue for 2026 or 2027 remains below the threshold could declare the reduction when calculating their tax liability.
The reduction would initially be calculated based on projected revenue. After the tax year ends, taxpayers would have to recalculate their liability using actual total revenue from all business activities.
If actual revenue exceeds VNĐ10 billion, the taxpayer would no longer qualify for the reduction and would have to pay back the amount of tax previously reduced without being charged for late payment.
Any overpaid tax could be offset against future liabilities or refunded in accordance with tax administration rules.
Entities eligible for a 30 per cent reduction in corporate income tax (CIT) payable would include companies established under the Law on Enterprises, cooperatives established under the Law on Cooperatives, public non-business units and other organisations established under the established law that conduct production or business activities and generate taxable income.
The reduction would be calculated on CIT payable after other tax incentives available to the taxpayer have been deducted.
Revenue for determining eligibility would include income from the sale of goods and provision of services, excluding revenue deductions, as well as financial income and other income.
For companies with dependent units or business locations, revenue would include the revenue of those units and locations as reported in consolidated annual financial statements.
Under the draft, businesses expecting annual revenue of no more than VNĐ10 billion in 2026 and 2027 would calculate the tax reduction themselves when making quarterly provisional CIT payments.
If actual annual revenue subsequently exceeds the threshold, the company would have to declare and pay the full tax amount.
The reduction is part of the effort to provide timely support to small-scale businesses and enterprises, which continue to face difficulties. Currently, household and individual businesses with annual revenues of less than VNĐ1 billion are exempt from value-added tax and PIT, while enterprises with revenues below VNĐ1 billion are exempt from CIT. — VNS
Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy