 Economy

GE Aerospace Signs Avionics Systems Service Support Agreement with FL Technics Indonesia
1.
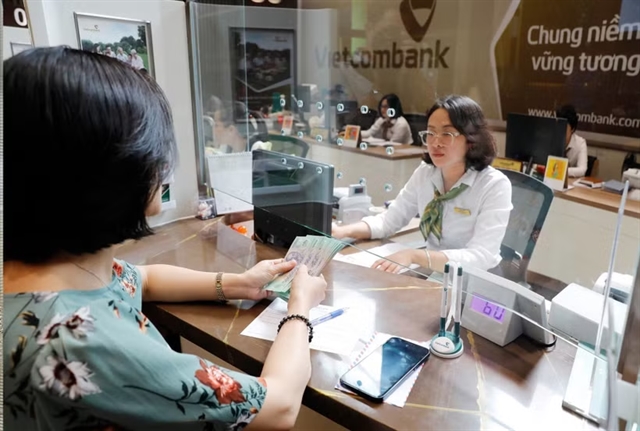 |
| A customer deposits money at a bank in Hà Nội. — VNA/VNS Photo |
HÀ NỘI — Việt Nam will need to build greater investor trust and create more convenient channels to convert household savings into long-term investment if it is to lift the net asset value of investment funds to around 5 per cent of GDP by 2030.
The Ministry of Finance aims to see about 500 investment funds by 2030, with 2.5 million investors holding fund certificates and the net asset value (NAV) of securities investment funds reaching approximately 5 per cent of GDP.
Techcom Capital CEO Phí Tuấn Thành estimated that if nominal GDP grows by around 10 per cent annually, assets equivalent to 5 per cent of GDP could reach approximately VNĐ1 quadrillion (US$38 billion) by 2030, nearly four times the current fund NAV of around VNĐ264 trillion.
While the target appears substantial, it represents less than one-tenth of more than VNĐ11 quadrillion currently held in household deposits.
Trịnh Quỳnh Giao, CEO of PVI Asset Management, said Việt Nam does not lack capital, given the large pool of household savings. The challenge is directing that money towards long-term investment.
She said that individual capital can be pooled and channelled back into the economy through three major groups of institutions: banks, insurers and investment funds. Banks have already established relatively high levels of trust, therefore bank deposits remain a familiar choice for most people.
For the fund management industry, a key challenge is encouraging households to move from savings or self-directed short-term investing towards accumulating assets through professional fund managers, particularly as Việt Nam seeks to restructure its stock market investor base.
Thành said four areas should be developed simultaneously to achieve the 5 per cent target: products, technology, distribution and investment performance.
Although more than 100 funds currently operate in the market, the gap between bank deposits and fund investment remains significant for many households.
Recently legalised money market funds could provide an entry point for investors accustomed to deposits, while low-cost index funds could serve those seeking long-term market exposure without continuously selecting individual stocks. Voluntary supplementary pension funds could address retirement savings.
Products could also be designed around specific financial goals, such as children's education, home purchases, retirement or long-term wealth accumulation, shifting investors' attention from daily NAV movements towards five-, 10-year or longer investment horizons.
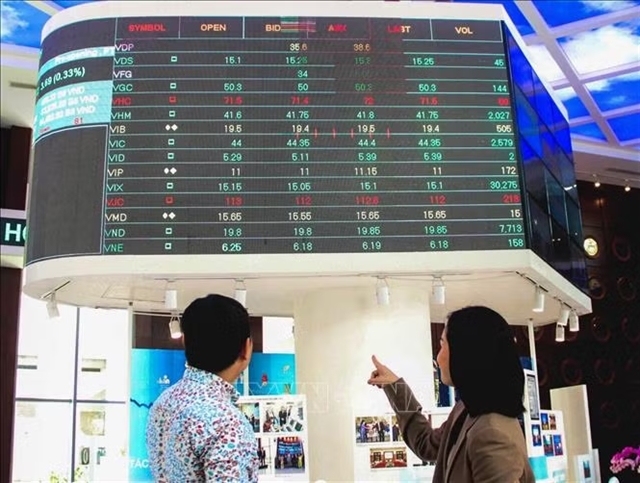 |
| Investors watch the market's performance on a digital screen in HCM City. — VNA/VNS Photo |
Technology represents another part of the process. Beyond simplifying account opening, electronic know-your-customer procedures, trading and payments, digitalisation can enable investment solutions to be tailored to investors' age, income, cash flows, financial objectives and risk tolerance.
Distribution also needs to expand through digital platforms, banks, insurers, securities companies and other partners with large customer bases. The potential outside Hà Nội and HCM City remains substantial, as fund certificate ownership is still limited.
Giao from PVI Asset said building trust could not be solely the responsibility of regulators. Market participants also need to strengthen investor education and work with the media, universities and relevant organisations to improve financial knowledge, with the longer-term objective of extending holding periods and gradually changing short-term investment habits.
Mekong Capital CEO Chad Ovel pointed to tax incentives as another potential mechanism for encouraging long-term capital. Developed markets can use tax policies to encourage retirement and long-term savings.
In the US, instruments such as 401(k) plans, individual retirement accounts and pension funds have contributed to retirement assets exceeding $45 trillion.
Singapore operates a supplementary retirement scheme under which participants receive tax incentives for long-term savings.
Ovel said Việt Nam could study similar mechanisms, including tax deductions for certain retirement investments or incentives for long-term fund investment. He also highlighted the need for a listing framework better suited to high-growth companies, which could broaden the supply of quality investment assets available to fund managers.
Việt Nam's transition to FTSE Russell secondary emerging market status from September 21 could also bring greater participation from international institutional investors, contributing to increasing liquidity, lifting up operating standards and raising demand for professional investment products.
Investment performance, however, remains an important test for the domestic fund industry.
According to Thành from Techcom Capital, a fund should not simply aim to top performance rankings over a quarter or a year, but should maintain consistent results across multiple market cycles, control risks and transparently measure its performance against benchmarks.
Strong returns during favourable market conditions may not be enough if excessive volatility and drawdowns during market reversals make it difficult for investors to remain invested over the long term and benefit from compounding.
Building sufficient trust to gradually channel part of the more than VNĐ11 quadrillion in household deposits into professionally managed, long-term investment products therefore remains central to the target of raising fund NAV to around 5 per cent of GDP. — BIZHUB/VNS
Economy
 Economy
 Economy
 Economy
.jpg) Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
.jpg)