 Politics & Law
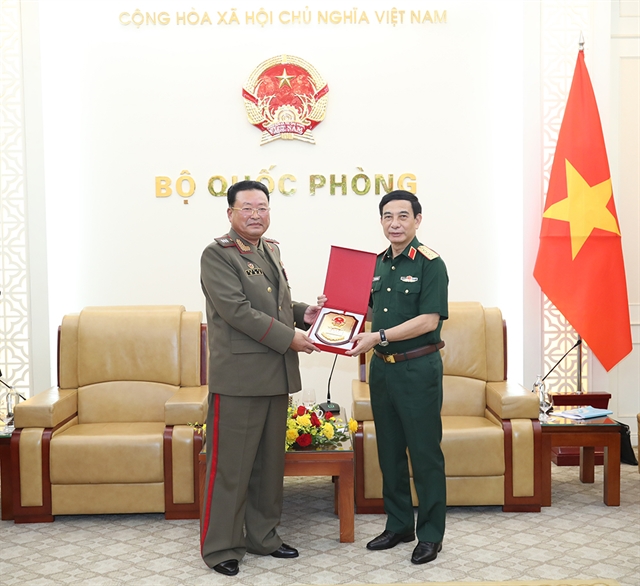
Defence ministries of Việt Nam, North Korea discuss strengthening bilateral defence cooperation
1.
|
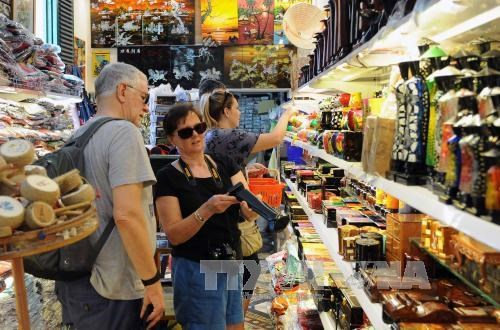
| Foreign tourists shop at a store in Việt Nam. — VNA/VNS Photo |
CIRCULAR No. 84/2026/TT-BTC
Providing value-added tax refund for goods purchased in Viet Nam by foreigners and overseas Vietnamese and carried by them upon exit
...
Article 10. Requirements, dossiers and procedures for selecting goods-selling enterprises and adjusting the status of goods-selling enterprises
1. To sell goods eligible for value-added tax refund, an enterprise must meet the following requirements:
a/ It is established and operates in accordance with Viet Nam’s law, is registered to sell goods eligible for value-added tax refund, and trades in these goods as prescribed in Clause 1 of Appendix IV to Decree No. 181/2025/ND-CP at one of the following locations:
a.1/ The head office of the enterprise;
a.2/ A branch of the enterprise;
a.3/ The location of an agent selling goods on behalf of the enterprise;
a.4/ A business location or shop of the enterprise.
b/ It complies with the regimes on accounting, invoices and records prescribed by law and declares and pays value-added tax by the credit method.
c/ It undertakes to participate in the System in accordance with Article 3 of this Circular.
2. Dossier for registration or adjustment of the status of a goods-selling enterprise:
a/ The enterprise or its branch shall submit to the tax authority directly managing the enterprise or branch, either directly or via the tax sector's information system for settling administrative procedures, a written request for registration or adjustment of its sale of goods, using Form No. 01/HTGTGT provided in Appendix I to this Circular;
b/ A goods-selling agent contract signed between the enterprise registering to sell goods and the agent selling goods on behalf of the enterprise (in the case of an agent selling goods on behalf of the enterprise): 1 copy.
3. Procedures for acceptance of dossiers for registration or adjustment of the status of a goods-selling enterprise:
a/ The enterprise or its branch shall submit the registration or adjustment dossier to the tax authority directly managing the enterprise or branch, either directly or via the tax sector's information system for settling administrative procedures. In case an enterprise’s branch located in a province or city other than that where the enterprise’s head office is located registers or adjusts its sale of goods eligible for value-added tax refund and declares value-added tax in a locality other than the province or city where the head office is located, the branch shall submit the registration or adjustment dossier to the tax authority directly managing the branch. In case an enterprise’s branch adopts centralised accounting at the head office and allocates the payable tax amounts to the provinces that are entitled to retain the corresponding revenue, the enterprise shall submit the registration or adjustment dossier to the tax authority directly managing the enterprise’s head office.
b/ The tax authority directly managing the enterprise or its branch shall receive and inspect the dossier and handle the case as follows:
b.1/ In case the dossier is incomplete, within 3 (three) working days from the date of receipt of the dossier, the tax authority shall issue a written notice requesting the enterprise to supplement the dossier;
b.2/ In case the dossier fails to meet the law-prescribed requirements, within 7 (seven) working days from the date of receipt of the complete dossier, the tax authority shall issue a written reply to the enterprise or its branch;
b.3/ In case the dossier is complete and meets the law-prescribed requirements, within 7 (seven) working days from the date of receipt of the complete dossier as prescribed, the tax authority directly managing the enterprise or its branch shall issue a written recognition, using Form No. 02/HTGTGT provided in Appendix I to this Circular, and send it to the enterprise or its branch and the relevant tax authority.
Article 11. Termination of the sale of goods eligible for value-added tax refund
1. At least 30 (thirty) days before the date of termination of the sale of goods eligible for value-added tax refund, an enterprise or its branch shall submit a written notice of termination of the sale of goods eligible for value-added tax refund to foreigners to the tax authority that accepted the enterprise's or branch's registration dossier, either electronically via the tax sector's information system for settling administrative procedures or directly.
2. Within 30 (thirty) days from the date of receipt of the written notice from the enterprise or its branch, the tax authority directly managing the enterprise or branch shall conduct an inspection and issue a written notice to the enterprise or branch, the relevant tax authority , the customs authority and the commercial bank of the termination of the enterprise's sale of goods eligible for value-added tax refund.
In case the enterprise or its branch violates the regulations on the sale of goods eligible for value-added tax refund specified in Clause 1, Article 10 of this Circular, the tax authority that accepted the enterprise's or branch's registration dossier shall consider and decide on the termination of the enterprise's sale of goods eligible for tax refund.
Upon termination of the sale of goods eligible for value-added tax refund, the enterprise shall remove the signs notifying that it sells goods eligible for value-added tax refund to foreigners displayed at its shops.
Article 12. Requirements and procedures for selecting commercial banks to act as value-added tax refund agents
1. Requirements: The commercial bank is licensed to conduct foreign exchange activities and provide foreign exchange services in accordance with the law on foreign exchange.
2. Selection procedures:
The commercial bank shall submit to the Customs Department the following documents:
a/ A written registration to act as a value-added tax refund agent for foreigners, containing information on the commercial bank's digital signature, including the digital certificate identification number, the name of the digital certificate service provider, the name of the person to whom the digital certificate is issued, the effective date, the expiry date and the public key, using Form No. 05/HTGTGT provided in Appendix I to this Circular;
b/ A document issued by the State Bank of Viet Nam certifying that the commercial bank is licensed to conduct foreign exchange activities and provide foreign exchange services: 1 copy.
3. The Customs Department shall receive and inspect the dossier submitted by the commercial bank.
a/ In case the dossier is incomplete, within 3 (three) working days from the date of receipt of the dossier, the Customs Department shall issue a written notice requesting the bank to supplement the dossier;
b/ In case the dossier fails to meet the law-prescribed requirements, within 5 (five) working days from the date of receipt of the dossier, the Customs Department shall issue a written reply to the bank;
c/ In case the dossier is complete and meets the law-prescribed requirements, within 7 (seven) working days from the date of receipt of the complete dossier, the Customs Department shall issue a written notice recognising the commercial bank as a value-added tax refund agent and provide an account for the commercial bank to access the System.
Article 13. Termination of status of value-added tax refund agents
1. In case a commercial bank has been recognised in writing by the Customs Department that it is a tax refund agent but wishes to terminate its tax refund agent status, it shall comply with the following provisions:
a/ Dossier: At least 60 (sixty) days before the date of termination of its tax refund agent status, the commercial bank shall send to the Customs Department a written request for termination of its tax refund agent status;
b/ Procedures:
b.1/ Within 10 (ten) working days from the date of receipt of the commercial bank's request, the Customs Department shall issue a written notice of termination of the commercial bank's tax refund agent status and send it to the tax authority, the State Bank of Viet Nam and relevant units;
b.2/ Upon termination of its tax refund agent status, the commercial bank shall remove the signs notifying that it acts as a value-added tax refund agent for foreigners at the tax refund service counters.
2. In case a commercial bank violates this Circular’s provisions on value-added tax refund, the Customs Department shall consider and decide to terminate its tax refund agent status.
a/ The Customs Department shall issue a written notice requesting termination of the commercial bank's tax refund agent status and send it to the tax authority, the State Bank of Viet Nam and relevant units;
b/ Upon termination of its tax refund agent status, the commercial bank shall remove the signs notifying that it acts as a value-added tax refund agent for foreigners at the tax refund service counters.
3. The Customs Department shall select another commercial bank as a replacement before issuing a written notice of termination of the commercial bank's tax refund agent status.
Article 14. Procedures for selecting international airports and international seaports for implementing value-added tax refunds for foreigners, and for suspending or terminating such implementation
1. An international airport or international seaport shall send to the Customs Department a written request for the implementation of value-added tax refunds for foreigners, including an assessment of economic efficiency and management requirements. Within 30 (thirty) days from the date of receipt of the request, the Customs Department shall issue a written notice on the implementation of value-added tax refunds for foreigners at the international airport or international seaport.
2. In case the implementation of value-added tax refunds for foreigners at an international airport or international seaport fails to ensure economic efficiency or meet management requirements, the Customs Department shall issue a written notice to suspend or terminate the implementation of value-added tax refunds for foreigners at that international airport or international seaport.
Article 15. Places of inspection of goods and invoices-cum-refund declarations, and places of payment of value-added tax refunds
1. The place of inspection of goods and invoices-cum-refund declarations shall be located in the baggage check-in area and/or the aircraft/ship boarding-pass inspection area and must satisfy the following requirements:
a/ Having sufficient floor space for the arrangement and inspection of goods and the inspection of invoices-cum-refund declarations;
b/ Having a separate counter (or kiosk) that meets safety and security requirements.
2. The place of payment of value-added tax refunds shall be located in the airside area of an international airport or the tax refund area of an international seaport, with a separate counter (or kiosk), and must satisfy the requirements for the management of money and accounting documents prescribed by law.
Chapter III
IMPLEMENTATION PROVISIONS
Article 16. Effect
1. This Circular takes effect on July 1, 2026, and replaces the Minister of Finance's Circular No. 72/2014/TT-BTC of May 30, 2014, providing value-added tax refund for goods carried by foreigners and overseas Vietnamese upon exit (below referred to as Circular No. 72/2014/TT-BTC), and Circular No. 92/2019/TT-BTC of December 31, 2019, amending and supplementing a number of articles of the Minister of Finance's Circular No. 72/2014/TT-BTC of May 30, 2014, except the cases specified in Article 17 of this Circular.
2. In case the legal documents referred to in this Circular are amended, supplemented or replaced, the amending, supplementing or replacing documents shall apply.
Article 17. Transitional provisions
1. Until the electronic customs data processing system meets the requirements for operation and the relevant systems are fully connected, Clauses 2, 3, 5 and 6, Article 1 of Circular No. 92/2019/TT-BTC of December 31, 2019, amending and supplementing Articles 4a, 6, 8 and 9 of the Minister of Finance's Circular No. 72/2014/TT-BTC of May 30, 2014, continue to apply.
2. For dossiers for the registration of goods-selling enterprises, and for adjustment or termination of the sale of goods eligible for value-added tax refund submitted before the effective date of this Circular, tax authorities shall continue to process such dossiers in accordance with this Circular.
Any difficulties or problems that arise in the course of implementation of this Circular should be promptly reported to the Ministry of Finance for timely resolution.-
For the Minister of Finance
Deputy Minister
NGUYEN DUC CHI
* The Appendix to this Circular is not translated.
<Source: Official Gazette, Issue Nos 80-84/2026>
<Part 1 is available at https://vietnamnews.vn/politics-laws/1800192/new-circular-on-vat-refund-for-foreigners.html>
Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law