 Politics & Law
MoET affirms foreign-language certificates remain valid in university admissions
1.
|
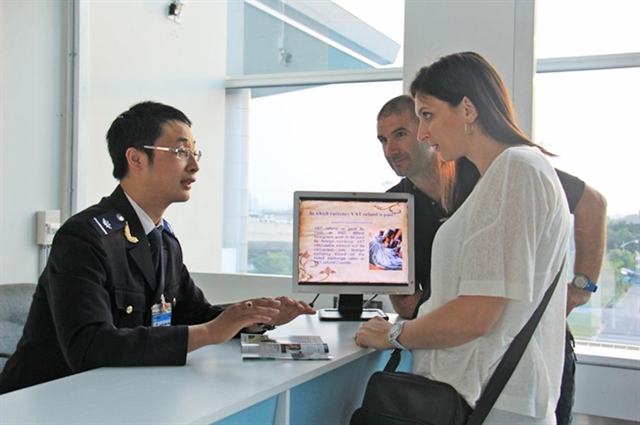
| Foreign visitors carry out VAT refund procedures at Tân Sơn Nhất International Airport. — Photo vietnamtourism.gov.vn |
CIRCULAR No. 84/2026/TT-BTC
Providing value-added tax refund for goods purchased in Viet Nam by foreigners and overseas Vietnamese and carried by them upon exit
Pursuant to Law No. 108/2025/QH15 on Tax Administration;
Pursuant to Law No. 48/2024/QH15 on Value-Added Tax; Law No. 149/2025/QH15 Amending and Supplementing a Number of Articles of the Law on Value-Added Tax; and Law No. 90/2025/QH15 Amending and Supplementing a Number of Articles of the Law on Bidding, the Law on Investment in the Form of Public-Private Partnership, the Law on Customs, the Law on Value-Added Tax, the Law on Export Duty and Import Duty, the Law on Investment, the Law on Public Investment, and the Law on Management and Use of Public Property;
Pursuant to the Government's Decree No. 252/2026/ND-CP detailing a number of articles of, and measures for organising and guiding the implementation of, the Law on Tax Administration;
Pursuant to the Government's Decree No. 181/2025/ND-CP detailing a number of articles of the Law on Value-Added Tax, which is amended and supplemented by the Government's Decree No. 359/2025/ND-CP and Decree No. 144/2026/ND-CP;
Pursuant to the Government's Decree No. 29/2025/ND-CP defining the functions, tasks, powers and organisational structure of the Ministry of Finance, which is amended and supplemented by the Government's Decree No. 166/2025/ND-CP;
At the proposal of the Director General of the Customs Department;
The Minister of Finance promulgates the Circular providing value-added tax refund for goods purchased in Viet Nam by foreigners and overseas Vietnamese and carried by them upon exit.
Chapter I
GENERAL PROVISIONS
Article 1. Scope of regulation
This Circular provides value-added tax refund for goods purchased in Viet Nam by foreigners and overseas Vietnamese and carried by them upon exit, as prescribed in Clause 5, Article 29 of the Government's Decree No. 252/2026/ND-CP of June 30, 2026, including:
1. Requirements, dossiers, and procedures for the selection of enterprises to sell goods eligible for value-added tax refund, and adjustment and termination of the sale of these goods.
2. Requirements and procedures for the selection of commercial banks to act as value-added tax refund agents, the termination of their status as value-added tax refund agents; the selection of international airports and international seaports for the implementation of value-added tax refunds, and for the suspension and termination of such implementation.
3. Regulations on access to, exchange of information and connection to the value-added tax refund management system for foreigners.
4. Regulations on places of inspection of goods and value-added tax invoices-cum-refund declarations, and places of payment of value-added tax refunds.
5. Regulations on the responsibilities and powers of relevant agencies, organisations and individuals in implementing value-added tax refunds.
Article 2. Subjects of application
1. Foreigners and overseas Vietnamese (below collectively referred to as foreigners), as prescribed in Article 33 of the Government's Decree No. 181/2025/ND-CP of July 1, 2025, detailing a number of articles of the Law on Value-Added Tax, who hold valid passports or international travel documents issued by foreign countries and use such documents to exit Viet Nam, purchase goods in Viet Nam and carry such goods abroad through border gates where value-added tax refunds are implemented.
2. Customs authorities, customs officers, tax authorities, tax officers, the State Treasury and State Treasury officers involved in the implementation of value-added tax refunds.
3. Enterprises selling goods eligible for value-added tax refund, including enterprises, branches and stores of enterprises, agents selling goods on behalf of enterprises, and business locations of enterprises and cooperatives (below collectively referred to as goods-selling enterprises).
4. Commercial banks acting as value-added tax refund agents (below referred to as commercial banks).
5. Other organisations and individuals involved in value-added tax refund as prescribed in this Circular.
Chapter II
SPECIFIC PROVISIONS
Article 3. The value-added tax refund management system for foreigners and access thereto
1. The value-added tax refund management system for foreigners (below referred to as the System) is a system which is developed, managed and operated by the Customs Department, and integrates, stores and exchanges information related to value-added tax refund for foreigners among the agencies, organisations and individuals specified in this Circular.
Data exchanged and processed on the System shall be regarded as legally valid data messages in accordance with the law on electronic transactions and must ensure their integrity and accessibility and enable the identification of their origin and the time of sending or receipt.
2. Agencies and organisations permitted to access, connect to and exchange information with the System include:
a/ Customs authorities;
b/ Tax authorities;
c/ Commercial banks;
d/ Goods-selling enterprises.
3. Access to, connection to and exchange of information through the System:
a/ Customs authorities, commercial banks and goods-selling enterprises shall use accounts issued by the customs authorities to access the System.
b/ Tax authorities shall provide and update information on goods-selling enterprises on the System by electronic means in accordance with Clause 2, Article 8 of this Circular.
c/ The System shall connect to and exchange information with the tax authorities’ electronic invoice system to serve the inspection and reconciliation of value-added tax invoices-cum-refund declarations (below referred to as invoices-cum-refund declarations).
d/ The Customs Department shall issue accounts and passwords for accessing the System, update information on changes thereto, and notify enterprises via the email addresses registered by the enterprises with tax authorities, and notify commercial banks via the email addresses registered with customs authorities, within 1 working day from the time of receipt of registration or adjustment information on goods-selling enterprises provided by tax authorities, and information on the registration of commercial banks as tax refund agents notified by the Customs Department.
The customs authority shall revoke a system user account within 1 working day from the time of receipt of the tax authority’s notice of the termination of a goods-selling enterprise’s status and the Customs Department’s notice of the termination of a commercial bank's status as a tax refund agent.
dd/ Goods-selling enterprises, commercial banks and customs authorities may access the System and change their system access passwords.
e/ Access to and exchange of information among units and organisations through the System must ensure compliance with the competence prescribed by the laws on electronic transactions, cyberinformation security, personal data protection and tax administration, and digital signatures must be used in accordance with the law on electronic transactions. The parties shall ensure information security and confidentiality during system connection.
g/ Customs authorities and tax authorities shall issue standard formats of data messages exchanged and connected between their respective systems.
4. The list of shared data and the input information fields of the System are provided in Appendix II to this Circular.
Article 4. Rights and obligations of foreigners
1. To receive value-added tax refunds for goods satisfying the requirements specified in Clause 1 of Appendix IV to Decree No. 181/2025/ND-CP and carried out of Viet Nam upon exit.
2. To receive guidance and relevant information and documents for the performance of their tax obligations and the exercise of their tax rights.
3. To check the information recorded on the invoices-cum-refund declarations issued by the goods-selling enterprises at the time of purchase.
4. To be responsible before law for the accuracy, legality and truthfulness of the passports or international travel documents presented to the goods-selling enterprises at the time of purchase; and of the passports or international travel documents, goods and invoices-cum-refund declarations presented to the customs authorities, and the dossiers presented to the commercial banks acting as tax refund agents upon exit.
5. To submit the invoices-cum-refund declarations and present the goods at least 30 minutes before the departure of the aircraft or vessels for inspection by the customs authorities.
6. To lodge complaints or initiate lawsuits against administrative decisions or administrative acts relating to their lawful rights and interests; to denounce violations of law committed by customs officers, tax officers and other relevant organisations and individuals in accordance with law.
Article 5. Rights and obligations of goods-selling enterprises
1. To use forms of publicity and advertising for the sale of goods eligible for value-added tax refund to foreigners upon exit in accordance with the law on advertising.
2. To register, and make adjustments to, the sale of goods at the registered addresses and take responsibility before law for the registration and adjustment of the sale of goods eligible for value-added tax refund. In case of termination of the sale of goods eligible for value-added tax refunds, to comply with Article 11 of this Circular.
3. To display signs notifying that the enterprises sell goods eligible for value-added tax refund (with the contents in Vietnamese and English), and remove such signs upon termination of the sale of goods eligible for value-added tax refund.
4. To receive guidance from tax authorities and customs authorities on matters related to value-added tax refund for foreigners.
5. To assist and guide foreigners in receiving value-added tax refunds for goods purchased in Viet Nam and carried by them upon exit.
6. Based on the information in the valid passports or international travel documents and the goods purchased, the goods-selling enterprise shall enter all information on the invoice-cum-refund declaration into the System, affix a digital signature, transmit the information specified in Appendix II to this Circular to the customs authority, print the invoice and hand it to the foreigner concerned. An invoice printed from the System may be used for presentation as an electronic invoice.
In case the System encounters a technical incident, making it inaccessible to an enterprise, the enterprise shall print the invoice-cum-refund declaration, sign and affix its seal thereto, and hand it to the foreigner concerned. The printed invoice serves as a basis for the customs authority to inspect and reconcile the information against the foreigner's goods.
Immediately after the System resumes normal operation, the goods-selling enterprise shall enter the information contained in the printed invoice into the System, ensuring that the invoice number, code and contents exactly match those shown on the printed invoice.
In case the customs authorities’ electronic data processing system is put into operation, the goods-selling enterprise shall update the invoice-cum-refund declaration already issued on the tax authorities’ electronic invoice system to the System and transmit it to the customs authority, print the invoice and hand it to the foreigner concerned. An invoice printed from the System may be used for presentation as an electronic invoice.
In case a goods-selling enterprise enters incorrect information on an invoice-cum-refund declaration, it shall comply with the law on invoices and records.
7. To register and use electronic invoices-cum-refund declarations in accordance with the law on invoices and records.
8. To be issued an access account and participate in the System in accordance with Article 3 of this Circular.
9. To submit quarterly reports on the sale of goods eligible for value-added tax refund to the tax authority, using Form No. 03/HTGTGT provided in Appendix I to this Circular.
10. To exercise other rights and perform other obligations in accordance with the Law on Tax Administration and other relevant laws.
Article 6. Rights and obligations of commercial banks
1. To receive guidance from customs authorities and tax authorities on the implementation of value-added tax refunds for foreigners.
2. To display signs notifying that the commercial bank acts as a value-added tax refund agent for foreigners at the tax refund service counter (with the contents in Vietnamese and English), and remove such signs upon termination of its status as a tax refund agent.
3. To receive a tax refund service fee when providing value-added tax refunds to foreigners in accordance with Clause 2 of Appendix IV to Decree No. 181/2025/NĐ-CP.
4. To declare and pay taxes as prescribed on the tax refund service fees received for providing value-added tax refunds to foreigners.
5. To inspect tax refund dossiers, arrange personnel and facilities, and advance and refund value-added tax amounts to foreigners in accordance with Clause 5 of Appendix IV to Decree No. 181/2025/ND-CP, and carry out payment procedures with the tax authority for the value-added tax amounts advanced in accordance with the law on the state budget and other relevant laws.
6. To sell freely convertible foreign currencies to foreigners eligible for tax refund in case they request conversion of the refunded value-added tax amounts into foreign currencies, and comply with the reporting regime prescribed by law.
7. To archive dossiers related to value-added tax refund for foreigners and dossiers related to the payment of advanced amounts and value-added tax refund service fees to foreigners in accordance with law.
8. To notify violations detected through the inspection of tax refund dossiers to competent agencies for handling in accordance with law.
9. To terminate its status as a tax refund agent when the Customs Department has selected another commercial bank as a replacement, thereby ensuring that value-added tax refund activities for foreigners continue without interruption.
10. To be issued an access account and participate in the System in accordance with Article 3 of this Circular.
11. To exercise other rights and perform other obligations in accordance with the Law on Tax Administration and other relevant laws.
Article 7. Responsibilities and powers of customs authorities
1. To assume the prime responsibility for disseminating information and providing guidance and explanations to foreigners, commercial banks and individuals and organisations involved in value-added tax refund for foreigners.
2. To inspect passports or international travel documents, invoices-cum-refund declarations, and goods presented by foreigners at the places of inspection of invoices-cum-refund declarations in accordance with Appendix IV to Decree No. 181/2025/ND-CP.
Customs inspection and supervision of value-added tax refund for foreigners shall be carried out in accordance with the Ministry of Finance's guidance on customs procedures, customs inspection and supervision, export duty and import duty, and tax administration applicable to exported and imported goods.
In case a foreigner presents an invoice-cum-refund declaration that has been adjusted or replaced in accordance with the law on invoices and records, the customs authority shall reconcile and verify each corresponding item of information based on the passport or international travel document and the information on the invoice-cum-refund declaration transmitted by the goods-selling enterprise to the System, the tax authorities’ electronic invoice system, and the regulations on goods eligible for tax refund specified in Clause 1 of Appendix IV to Decree No. 181/2025/ND-CP.
3. The head of the border-gate customs authority may decide whether to accept an invoice-cum-refund declaration and goods presented after the deadline prescribed in Clause 5, Article 4 of this Circular.
4. The border-gate customs authority shall update the information specified in Appendix II to this Circular on the System.
5. The Customs Department shall receive dossiers submitted by commercial banks and select commercial banks to act as tax refund agents or terminate the tax refund agent status of commercial banks in accordance with Articles 12 and 13 of this Circular; and receive dossiers submitted by international airports and international seaports requesting the implementation, suspension or termination of the implementation of value-added tax refunds for foreigners at such international airports and international seaports in accordance with Article 14 of this Circular.
6. The Customs Department shall develop, manage, operate and use the System in accordance with Article 3 of this Circular. In case the System encounters a technical incident, the customs authority shall issue a notice, using Form No. 04/HTGTGT provided in Appendix I to this Circular, on the customs portal (www.customs.gov.vn) to inform relevant units.
7. To connect the System to the tax authorities’ electronic invoice system.
8. On the same working day or no later than the following working day, the customs authority shall notify in writing the provincial/municipal Tax Office managing the goods-selling enterprise selling goods of the following cases:
a/ The enterprise fails to issue or update an invoice-cum-refund declaration on the System, or issues or updates an invoice-cum-refund declaration but fails to transmit it to the System, unless the System encounters a technical incident as prescribed in Clause 6, Article 5 of this Circular;
b/ The enterprise issues an invoice-cum-refund declaration containing information that is not complete or accurate as prescribed by the law on invoices and records, or information that is incomplete, inaccurate or inconsistent with the actual goods;
c/ The enterprise violates this Circular’s provisions on value-added tax refund.
9. To settle complaints and denunciations relating to the implementation of value-added tax refunds for foreigners within the scope of their assigned responsibilities.
10. To impose penalties or propose competent agencies to impose penalties for violations of regulations on value-added tax refund for foreigners in accordance with law.
11. To perform other responsibilities and exercise other powers in accordance with the Law on Tax Administration and other relevant laws.
Article 8. Responsibilities and powers of tax authorities
1. To assume the prime responsibility for providing support, disseminating information and providing guidance and explanations to goods-selling enterprises and individuals and organisations involved in value-added tax refund for foreigners.
2. To receive dossiers and select goods-selling enterprises, adjust or terminate the status of goods-selling enterprises in accordance with Articles 10 and 11 of this Circular. To publish the list of goods-selling enterprises and the list of enterprises terminating their status of goods-selling enterprises on the Portal of the Tax Department and the portals of provincial/municipal Tax Offices which recognise goods-selling enterprises, adjust or terminate the status of goods-selling enterprises, on the same working day or no later than the beginning of the following working day from the date of issuance of the document on such recognition, adjustment or termination in accordance with Articles 10 and 11 of this Circular; at the same time, to affix a digital signature to and electronically transmit information on goods-selling enterprises to the System in accordance with Appendix II to this Circular.
3. Immediately upon receipt of information from the customs authority on goods-selling enterprises as prescribed in Clause 8, Article 7 of this Circular, the tax authority shall inspect and reconcile the information and process the information in accordance with law.
4. To receive and process tax refund dossiers and transfer them to the State Treasury for payment of the value-added tax amounts advanced by commercial banks for refund to foreigners and the tax refund service fees to which commercial banks are entitled, in accordance with the law on tax administration.
5. To participate in and connect to the System in accordance with Article 3 of this Circular.
6. To coordinate with customs authorities in connecting the tax authorities’ electronic invoice system to the System.
7. To perform other responsibilities and exercise other powers in accordance with the Law on Tax Administration and other relevant laws.
Article 9. Responsibilities and powers of the State Treasury
1. To transfer to commercial banks the value-added tax amounts advanced by such commercial banks and the tax refund service fees to which such commercial banks are entitled, in accordance with the law on the state budget and other relevant laws.
2. On a monthly and annual basis, to reconcile with tax authorities and certify reports on value-added tax refund data as prescribed.
3. To coordinate in settling complaints and denunciations relating to the payment of value-added tax refunds to foreigners within the scope of its assigned responsibilities.
4. To perform other responsibilities and exercise other powers in accordance with law.
...
(To be continued)
* Source: Official Gazette, Issue Nos 80-84/2026
Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law
 Politics & Law