 Economy
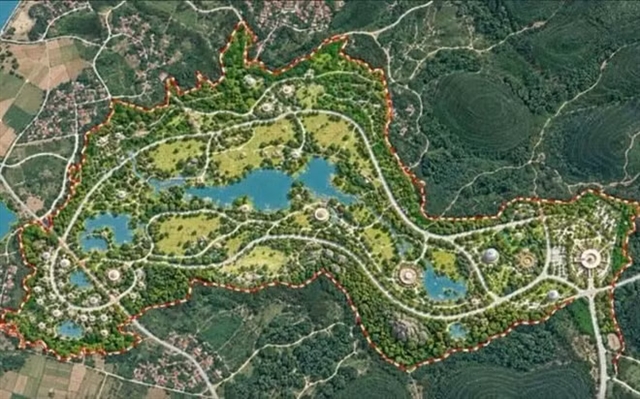
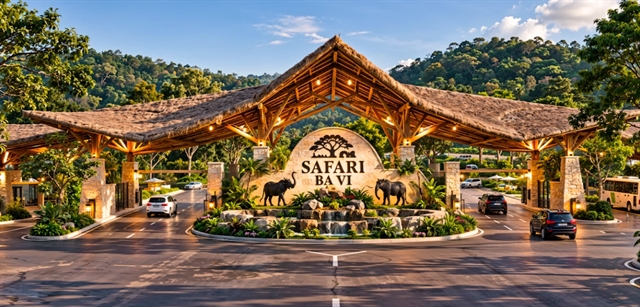
Hà Nội breaks ground on 299-ha safari park
1.
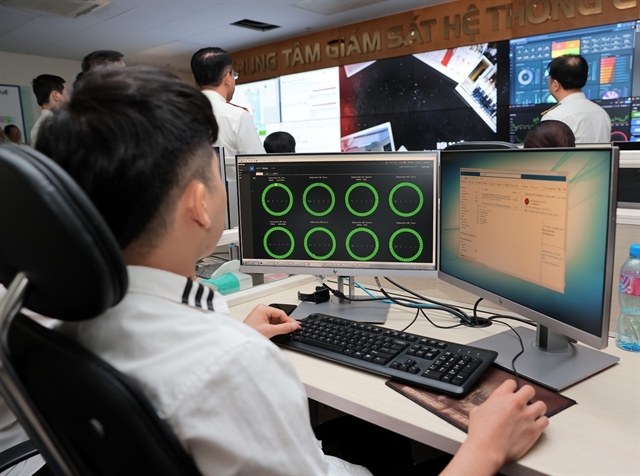
|
| At the Information Technology Monitoring Centre of the Department of Taxation. — VNA/VNS Photo Phạm Hậu |
HÀ NỘI — The Ministry of Finance has asked provincial and municipal finance departments to accelerate business dissolution procedures, with tax authorities required to respond to business registration agencies within two working days of receiving relevant information.
In a document sent to local finance departments nationwide on October 12, the ministry urged provincial business registration authorities to coordinate closely with tax agencies to expedite the processing of dissolution applications.
This is part of the nationwide campaign to clean up tax codes and accelerate business closure to improve the business environment and strengthen tax administration amid Việt Nam’s ongoing digital transformation.
Under the established regulations, provincial business registration agencies must process dissolution applications and notify tax authorities within one working day of receiving an application.
If tax authorities confirm within the prescribed period that a company has fulfilled its tax obligations, the business registration agency must update the company’s legal status in the national business registration database to “dissolved” within one working day of receiving the confirmation.
If no response is received from the tax authority within two working days of the notification, the registration agency must change the company’s legal status to “dissolved” within one working day after the response deadline expires.
For companies failing to submit dissolution applications, if no dissolution application, application to terminate the operations of a branch, representative office or business location, or written objection from tax authorities or other relevant parties is received within 180 days, the provincial business registration agency must update the company’s status to “dissolved.”
The status of the company’s branches, representative offices and business locations must also be updated to “operations terminated” within one working day after the 180-day period expires.
Where technical problems occur or information is not transmitted or received promptly, business registration agencies and tax authorities must coordinate and exchange information through appropriate channels. — BIZHUB/VNS
Economy
 Economy
 Economy
 Economy
.jpg) Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
.jpeg) Economy
 Economy
 Economy