 Economy
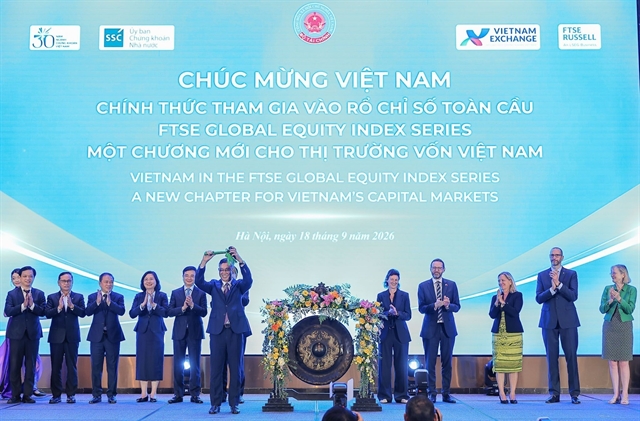
Việt Nam marks entry into FTSE global emerging-market index
1.
|
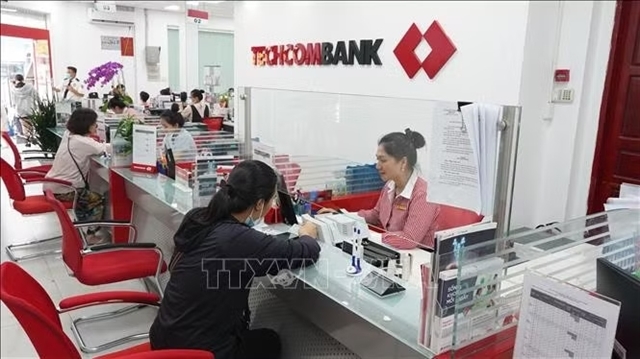
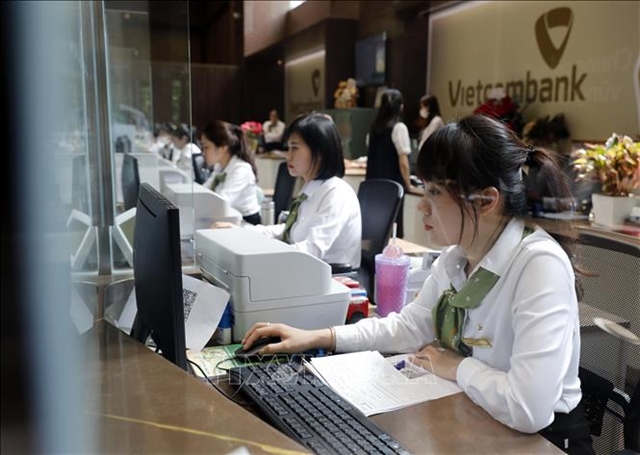
| Previously, credit institutions and voluntary organisations were permitted to access credit information services based on contracts signed with the Credit Information Centre of Vietnam. —VNA/VNS Photo |
HÀ NỘI — Banks are allowed to share credit information only after getting customer consent from November 1 this year, according to a newly issued policy from the State Bank of Vietnam (SBV).
Under Circular 46/2026/TT-NHNN, which amended and supplemented certain articles of Circular 15/2023/TT-NHNN regarding the SBV's credit information activities, the SBV clearly stipulated that the provision and sharing of credit information require the explicit consent of the customer.
The new circular amended and supplemented regulations on the entities authorised to receive credit information and the scope of information provided. It stipulates that the provision of credit information regarding borrowers to voluntary organisations, foreign credit information organisations and other groups requires the borrower's consent in accordance with relevant laws, while ensuring compliance with contracts and agreements with the CIC.
Previously, credit institutions and voluntary organisations were permitted to access credit information services based on contracts signed with the Credit Information Centre of Vietnam (CIC), while foreign credit information organisations could provide, use and exchange credit information products regarding borrowers in accordance with agreements with the CIC and legal regulations.
This meant that only groups other than those previously mentioned were required to obtain the borrower's consent when accessing credit information services regarding that borrower.
According to the new regulations, customer consent must be expressed in a clear and specific manner and be able to be printed or reproduced in writing, including in electronic or verifiable formats.
In addition, the new circular stipulates that the provision of credit information must be carried out in the form of electronic data in accordance with the credit information indicator system. In cases where certain indicators or the entire set of indicators cannot be provided as electronic data, credit institutions and voluntary organisations may provide them in writing, subject to agreement with the CIC.
As for timelines, under the new circular credit institutions must submit data according to the frequency specified in the credit information indicator system issued alongside the decisions of the SBV governor, while voluntary organisations must do so based on the frequency stipulated in their information exchange agreements with the CIC. — BIZHUB/VNS
Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy
 Economy